
First, a bit of context… I first looked at cruise lines in 2020 during a very difficult period for the businesses. In general, they have managed through wonderfully, but RCL has clearly set themselves apart in the years since in handling a large debt load and rapidly expanding ROIC.
I'm looking to make room and may add soon.
The deal
RLC closed Monday at $250, Sandals rumors hit Tuesday, deal signed Wednesday, stock -10% since. Oil and rates also not helpful today. ~$61bn market cap paying $3bn for 50% of Sandals and Beaches Resorts… but they lost ~$6bn in market cap… safe to say some big shareholders were caught off guard….
Why buy a Caribbean beach resort
Share of wallet! RCL’s deal deck statesRCL captures 20–25% of its guests' five-year vacation spend. The ships are already full, and they’ve shown a consistent ability to fill new berths (2 new ships in ‘26, 1 in ‘27, 3 in ‘28, and entering river cruises). So the next dollar has to come from the same household’s other trips.
Structure… 50/50 board, equity method so JV debt stays off RCL’s balance sheet, Morgan Stanley committed financing, close early 2027, accretive to 2027 earnings per RCL
Wallet is the constraint.. 110% load factor in 2Q26, 57% of 2026 capacity in the Caribbean
Missing trip type is beach all-inclusive… ~30% overlap between RCL guests and Caribbean resort travelers over 2yrs, booked as an extra trip rather than a swap
Faster growth segment… Caribbean all-inclusive spend $9bn in 2019 to $16bn in 2025 for 11% CAGR, against RCL capacity of 4-7% guided for 2027-29
Best asset base in the basin… 18 resorts and 6,155 keys, 7 of them in Jamaica, 3 more Beaches coming
Founder’s son Adam Stewart stays executive chairman
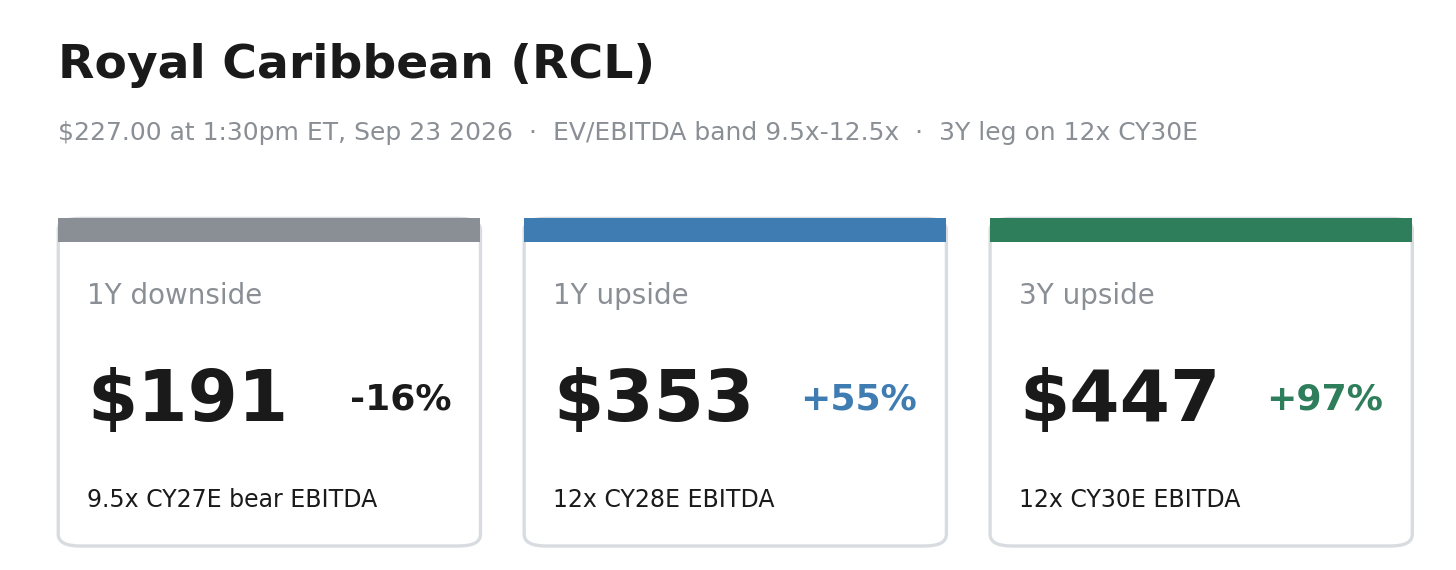
RCL paid ~10x forward EBITDA, which is ~$600mm EBITDA for the whole company and ~$975K per key. Hyatt (H) paid 8.5-9.5x stabilized ‘27 EBITDA in 2025 for Playa’s management contracts, asset-light, with no owned real estate. RCL itself trades at 9.6x CY27E EBITDA pro forma… so what’s the big deal? This is likely accretive to their mid-teens ROIC over a few years. And what happens if they get to know the asset and buy in the whole thing as they did before (Silversea).
Where the multiple sits
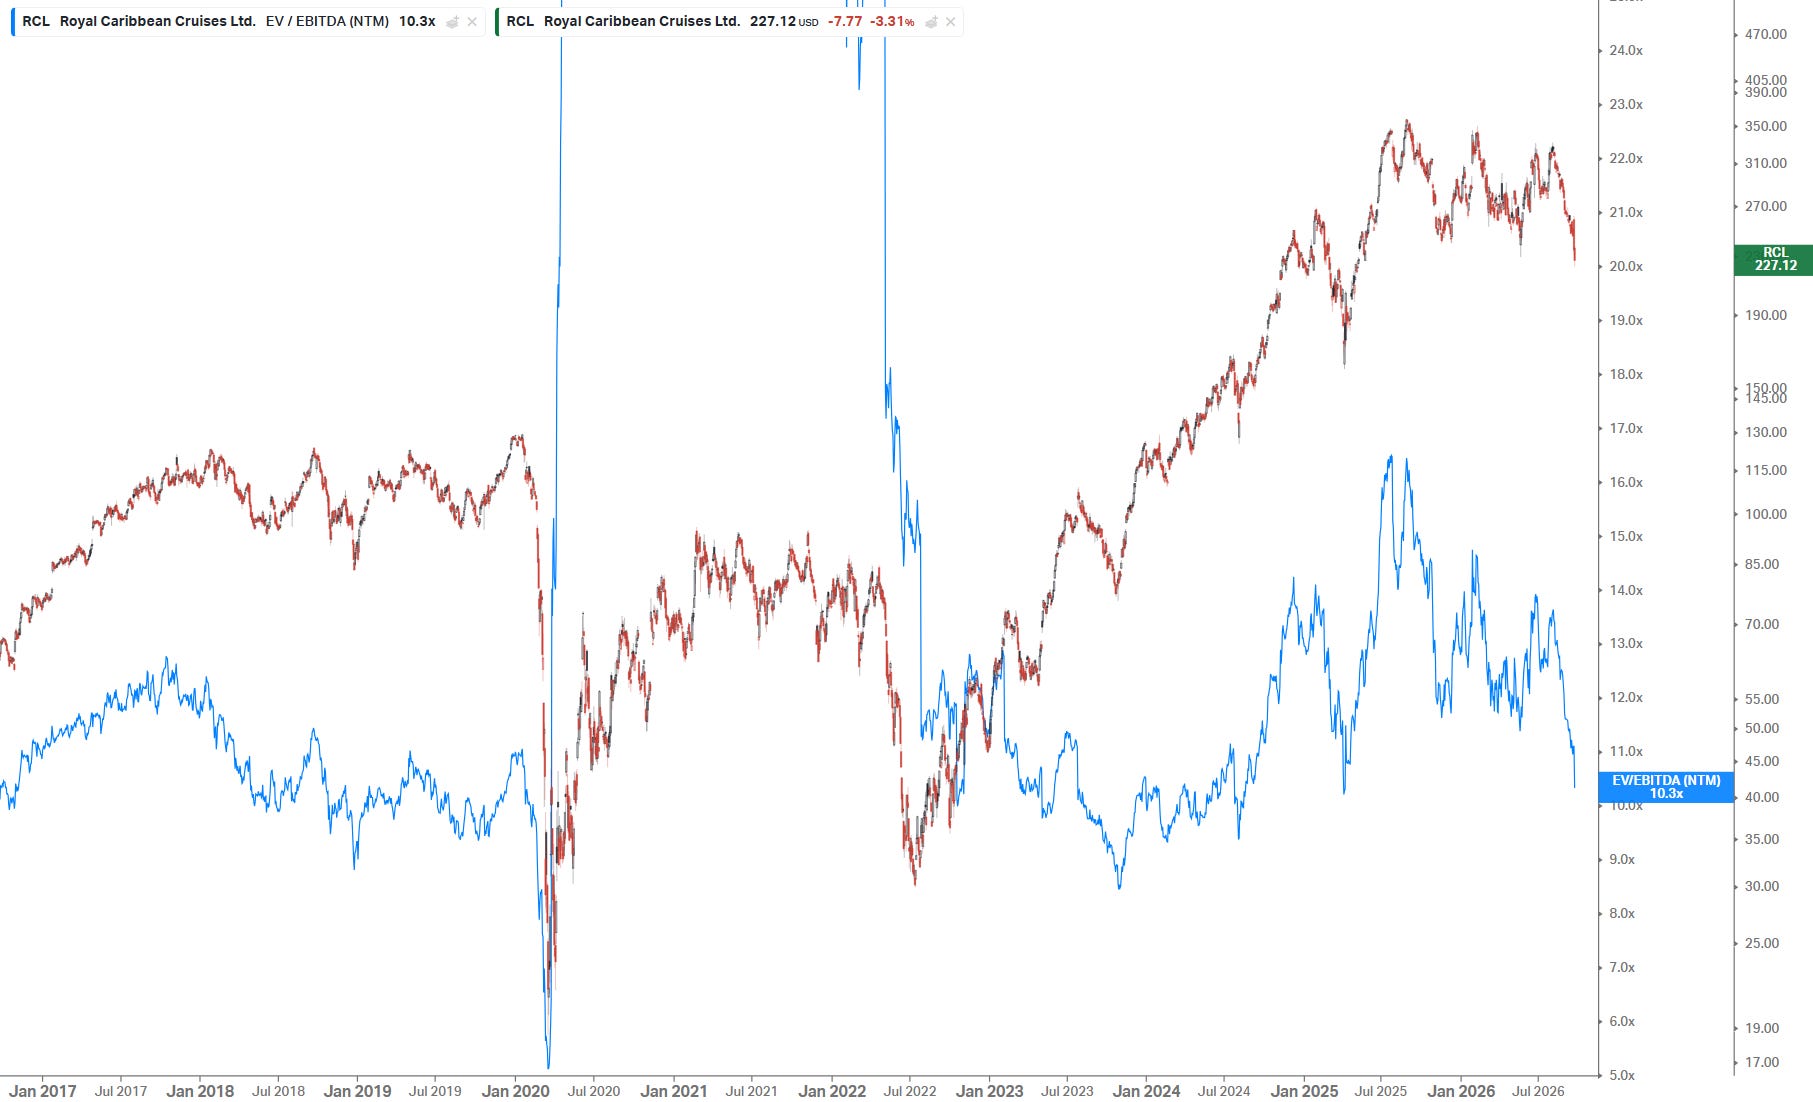
Assume the world doesn’t end, oil and rates don’t stay here forever, boomers keep spending their interest income on cruises, and mass AI job losses don’t occur… backsolve from target 12x ‘27 EBITDA and the market is paying for $7.1bn of 2027 EBITDA. That is 8% below this year's $7.7bn guide and 15% below ‘28 consensus. The sell-side is actually quite good at modeling cruise lines and typically takes forward curves for fuel and have a good view into booking curves and yields out several quarters. Let’s assume the world doesn’t end and that consensus is a good starting point, which I firmly believe it is… the market is now giving them no credit for potential upside from the deal… let’s walk through that below. Better yet, RCL says 2027 bookings are “pacing ahead of historical levels” at higher prices and 53% of 2027 fuel is hedged at $405/t. A 2027 net yield guide below +1% in February changes it.