

Since we last published, compute prices kept rising and supply got tighter. The market has also stopped paying for megawatts funded with new paper. It now pays for pricing power.
Bottom line…
Pricing is still rising... 5yr market rate is now ~$19bn per GW-year (and is our GOOGL base case), short-term capacity clears at ~$40bn with two witnesses, and NBIS lifts list prices 17-21% from Oct 1st
Market discriminating... big lease and capacity announcements that arrive with new debt or equity now fade or fall, pricing news without a raise still rallies, 9/17 the market graded both on the same morning
Money got more expensive for the levered players… CRWV’s new convertible costs about 10.5-11.7% once the equity option is valued, up ~170bp from its April deal
Supply got tighter again... Oracle’s New Mexico Stargate campus now carries a force majeure notice and a reported one-year slip, and Texas has frozen data-center permits pending a grid audit
Thesis intact - owns integration and NBIS…
Compute keeps getting more expensive
Revenue per gigawatt-year by deal... bold green rows are new since our Google note…
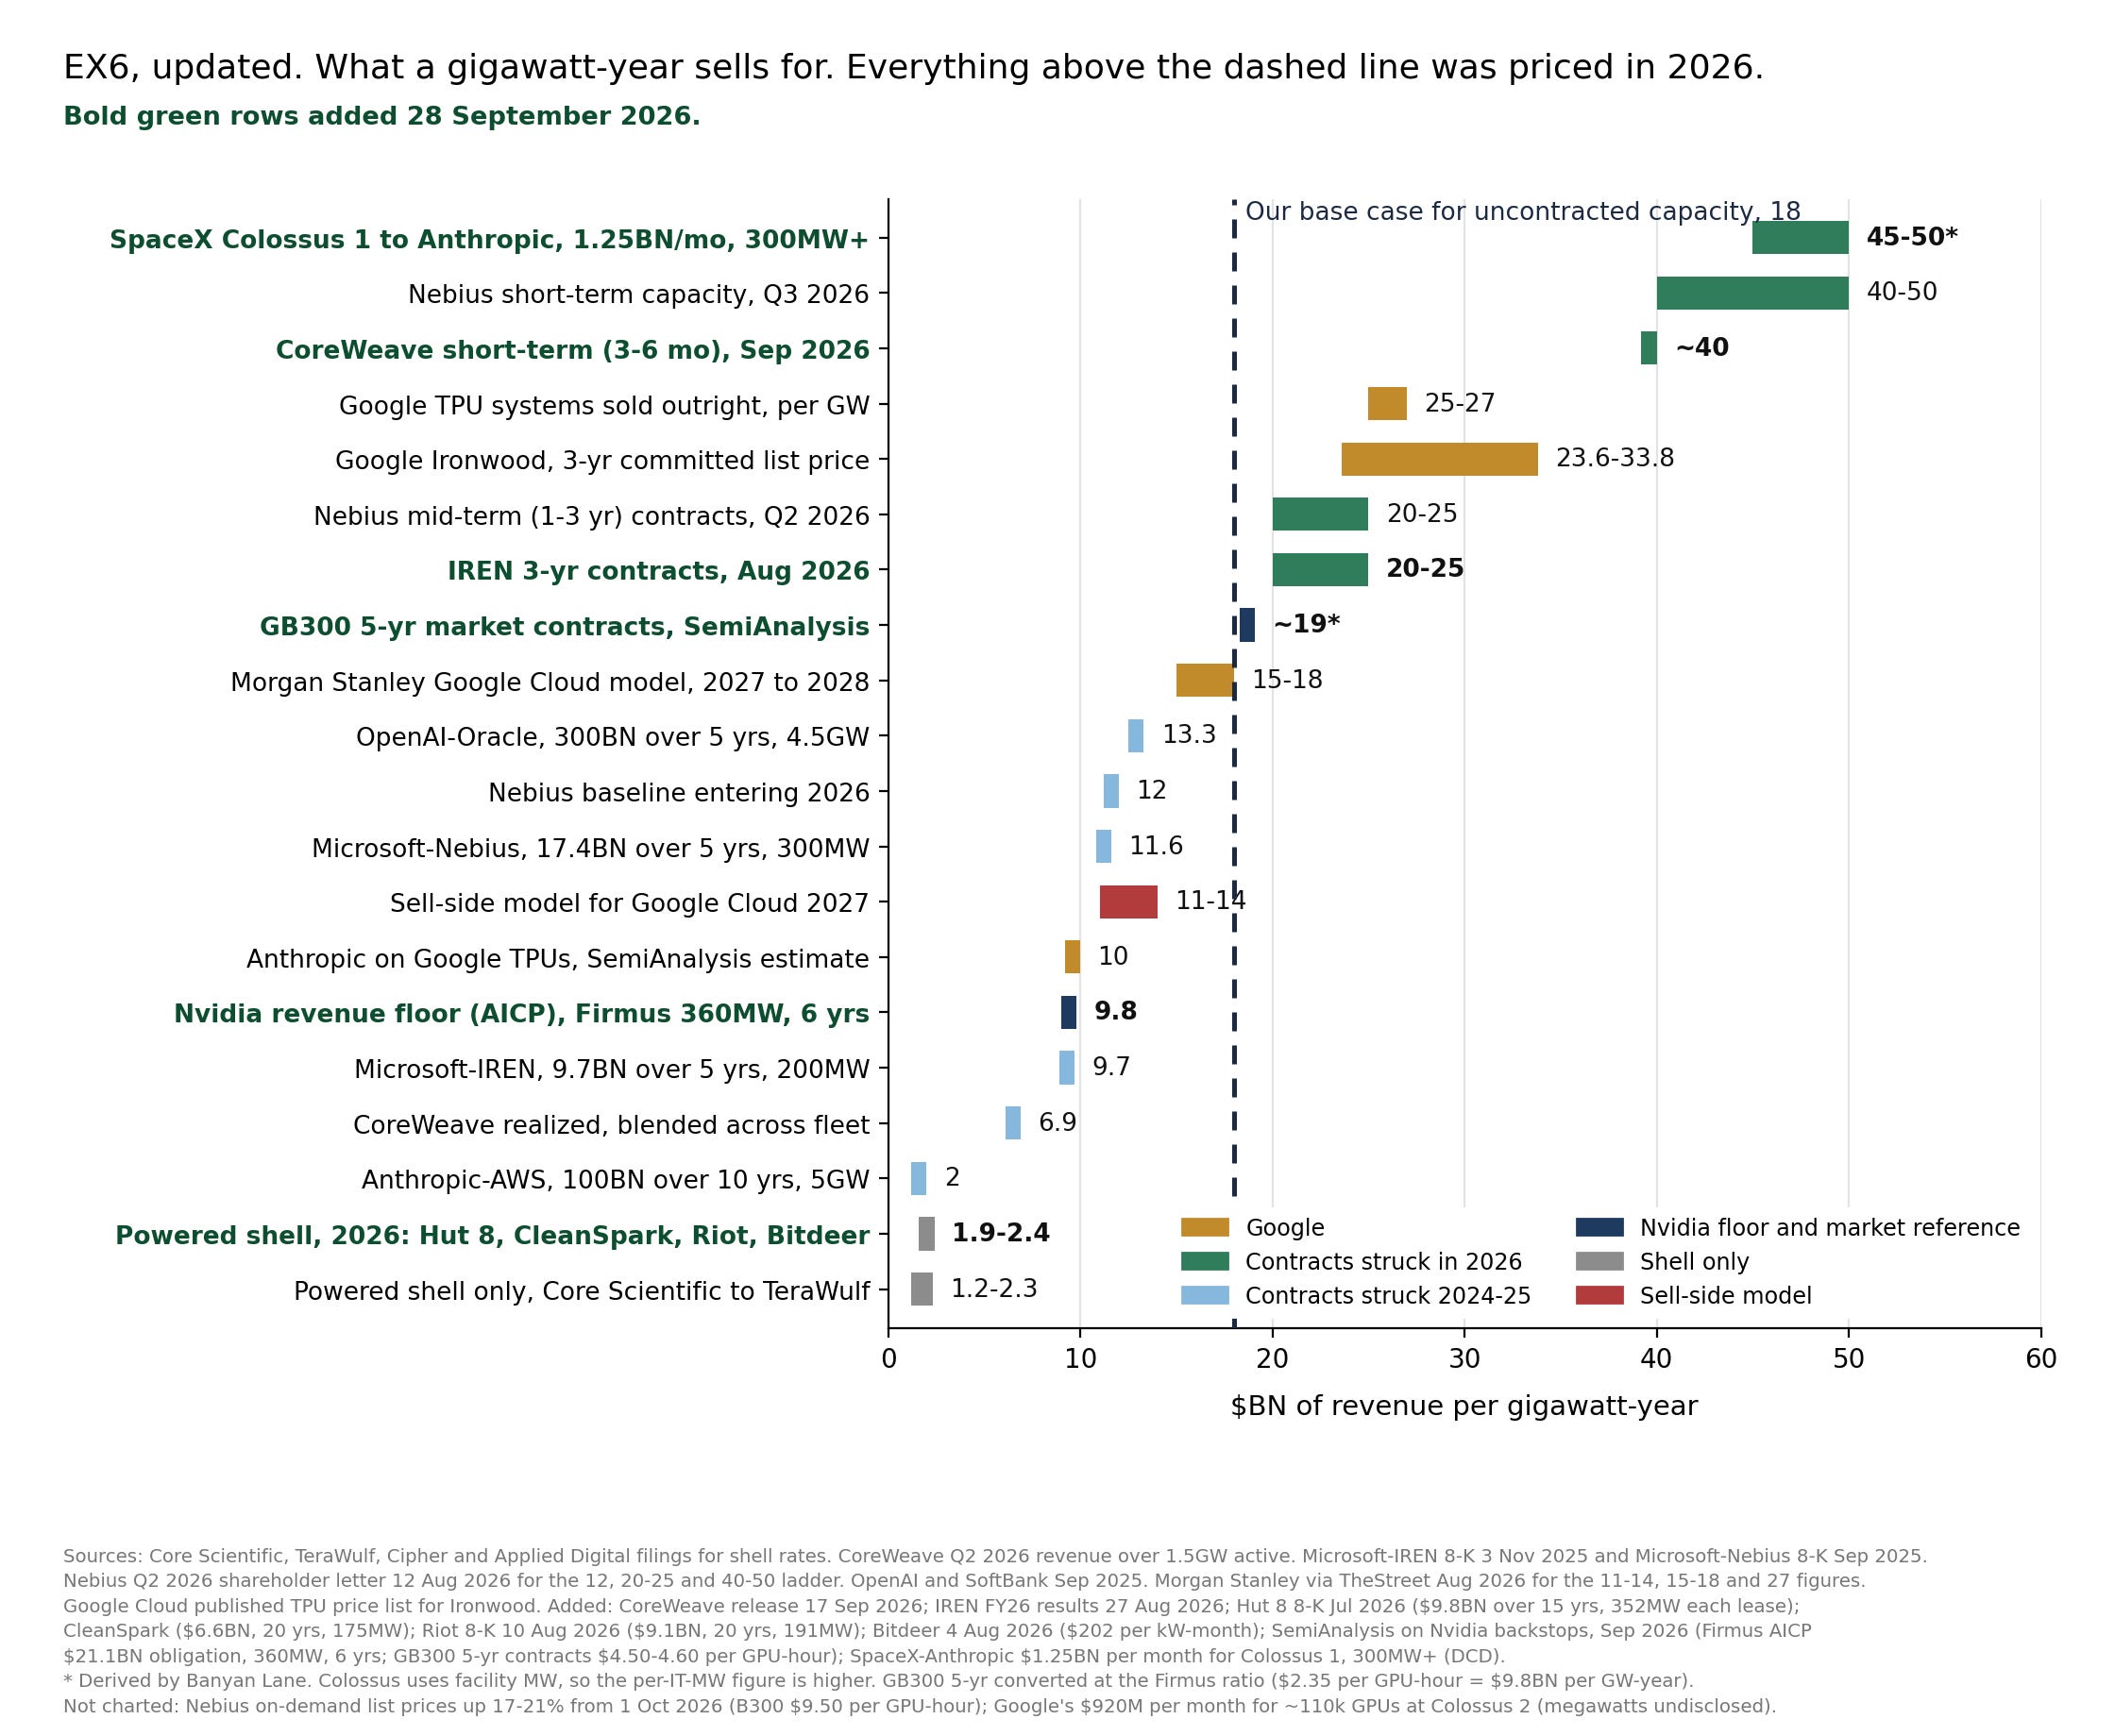
The market five-year rate now sits on our base case... SemiAnalysis puts five-year GB300 contracts at $4.50 to 4.60 per GPU-hour, about $19bn per GW-year, against our $18bn base case for uncontracted capacity
Short-term pricing has two new marks… CoreWeave’s 3-6 month contracts at ~$40bn per GW-year (Sep 17) match Nebius’s short-term tier of $40-50bn
Top of the market is SpaceX... Anthropic pays $1.25bn a month for Colossus 1, roughly $45 to 50bn per GW-year on 300MW+… that is immediacy pricing on sunk capex, with a 90-day termination right after December
Nebius has set its 2027 baseline… 4 mid-term deals (Reflection, Cohere, a US lab, a quant firm) average over $1bn each at $20-25bn, with 50 to 60% of capex prepaid and payback of 1 year 10 months... management says it could sell all of its 2027 capacity on those terms… IREN matches with >$20bn signed, ~$25bn in talks, 45 to 55% prepaid
Nvidia’s floor is half the market... AICP backstop at Firmus works out to ~$9.8bn, about where 2024-25 contracts were struck... that is how far pricing would have to fall before Nvidia’s guarantee pays
Shell rent barely moved… $1.9-2.4bn on 2026 leases, versus $1.2-2.3bn before… All of the price action is at the operator layer
List prices too... Nebius raises on-demand prices 17-21% from 1 October (B300 $7.85 to $9.50 per hour), its second increase in about three months
Market stopped paying for megawatts
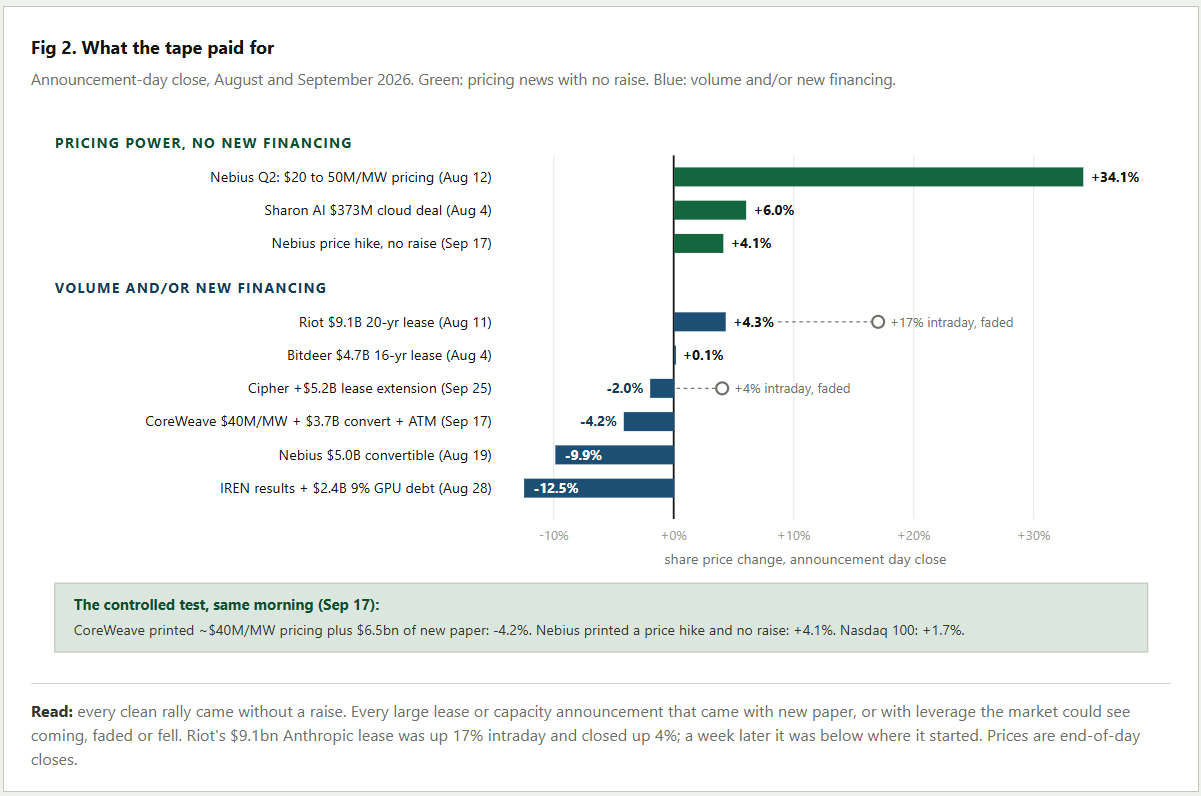
Why the change… a 20yr lease at $2.4M per MW, funded at 80 to 90% loan-to-cost, is now read as a financing event, not a growth event. The equity is a thin slice on top of project debt, and that debt got dearer.
Cost of paper is rising… see CoreWeave’s April convertible details above, IREN’s new GPU debt is 9.0% fixed.
Rates moved against them... Fed hike and a 10-year 5.25% hit the most levered names hardest
Nebius is not immune... fell 10% on its own $5bn convertible on Aug 19, Nebius’s news is more often pricing, and its prepaid deal structure means less of its growth has to be funded with paper
Hyperscalers split the same way...
Alphabet was up 1.3% in September, moved by product competition not capex, TPUs are now bankable collateral with a reported $22bn bank loan secured by TPUs and customer contracts for Crux AI
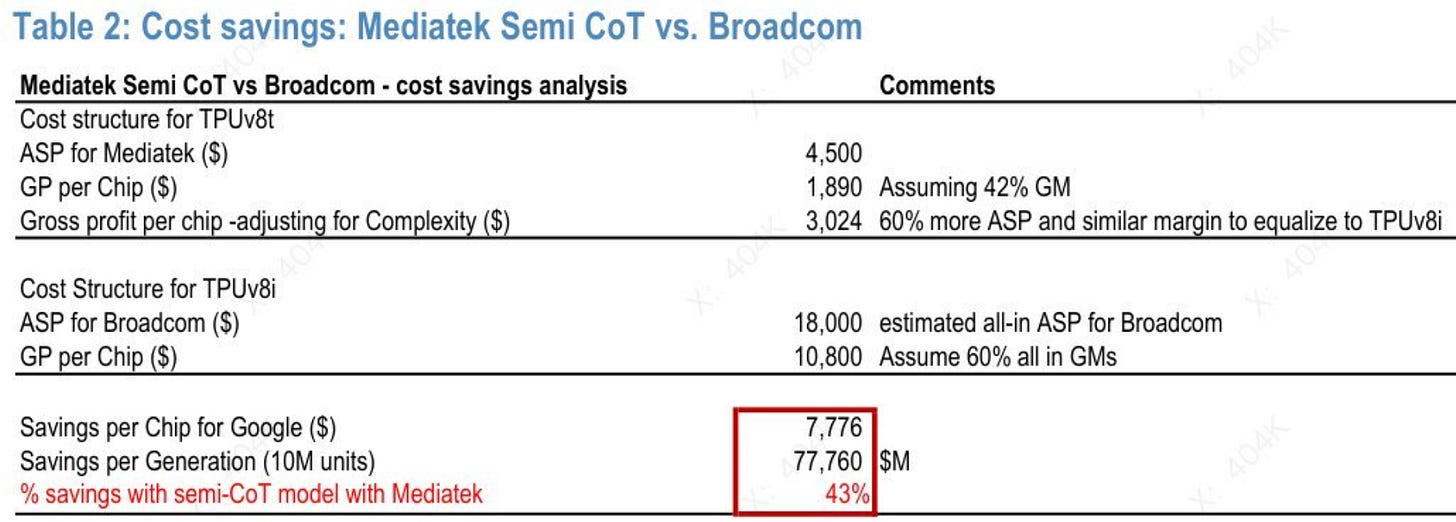
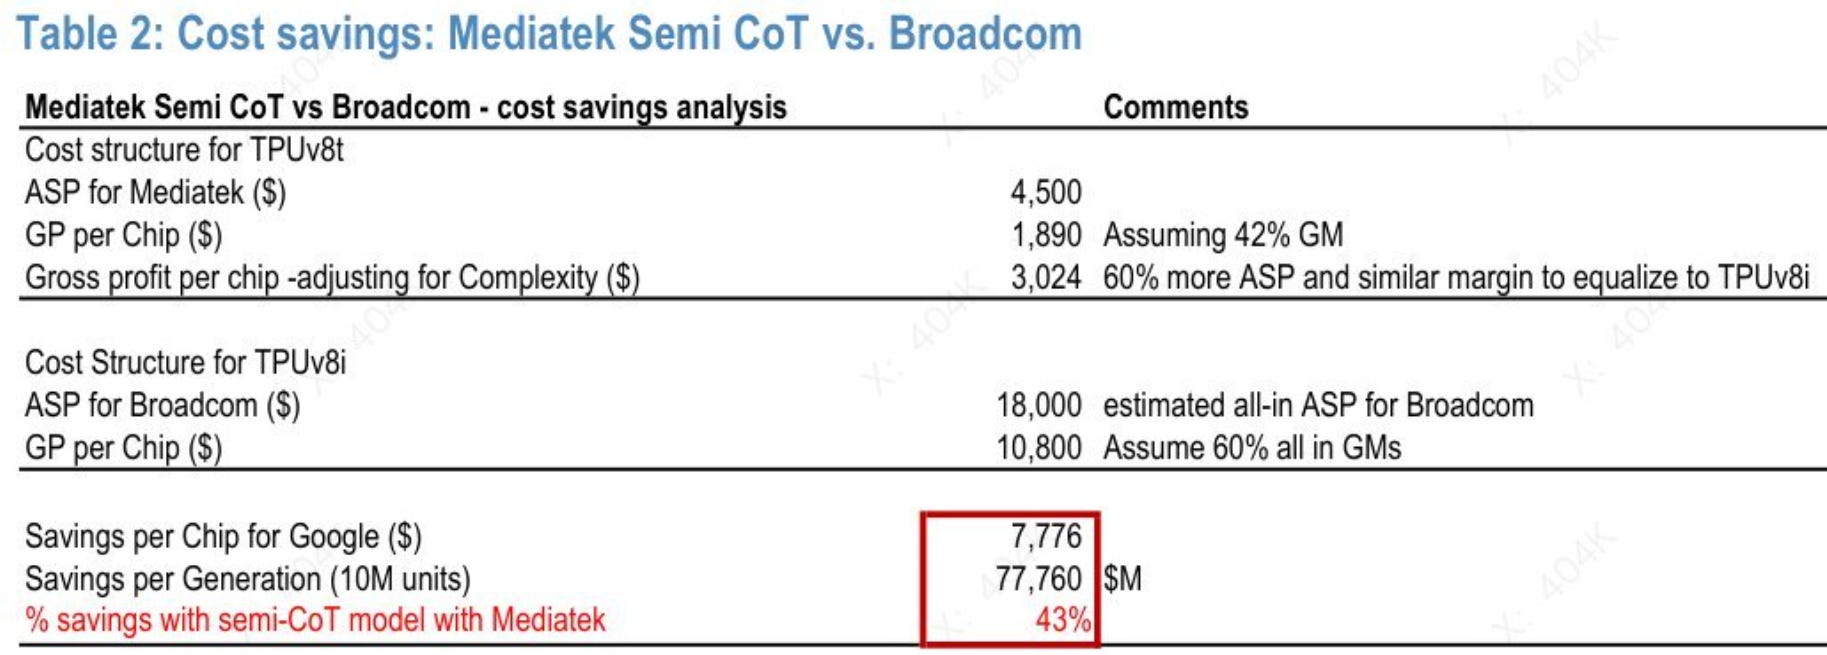
Better yet, TPU costs reportedly coming down 43% via switch to MediaTek (per JPM)
Oracle, the debt-funded, customer-concentrated hyperscaler, fell 8% month to date against the S&P’s +0.6%
Nscale’s IPO filing shows $103bn of contract value, about 85% of it from Microsoft and Anthropic
NM, TX and grid got tighter again
Oracle and OpenAI’s Project Jupiter in Doña Ana County was meant to be ~2.2 GW of 2028 capacity. The power plan is now ~2.45 GW of Bloom fuel cells running on gas (turbines were dropped in April), so one 17.8-mile pipeline is the critical path, and a one-mile crossing of state land is the choke point.
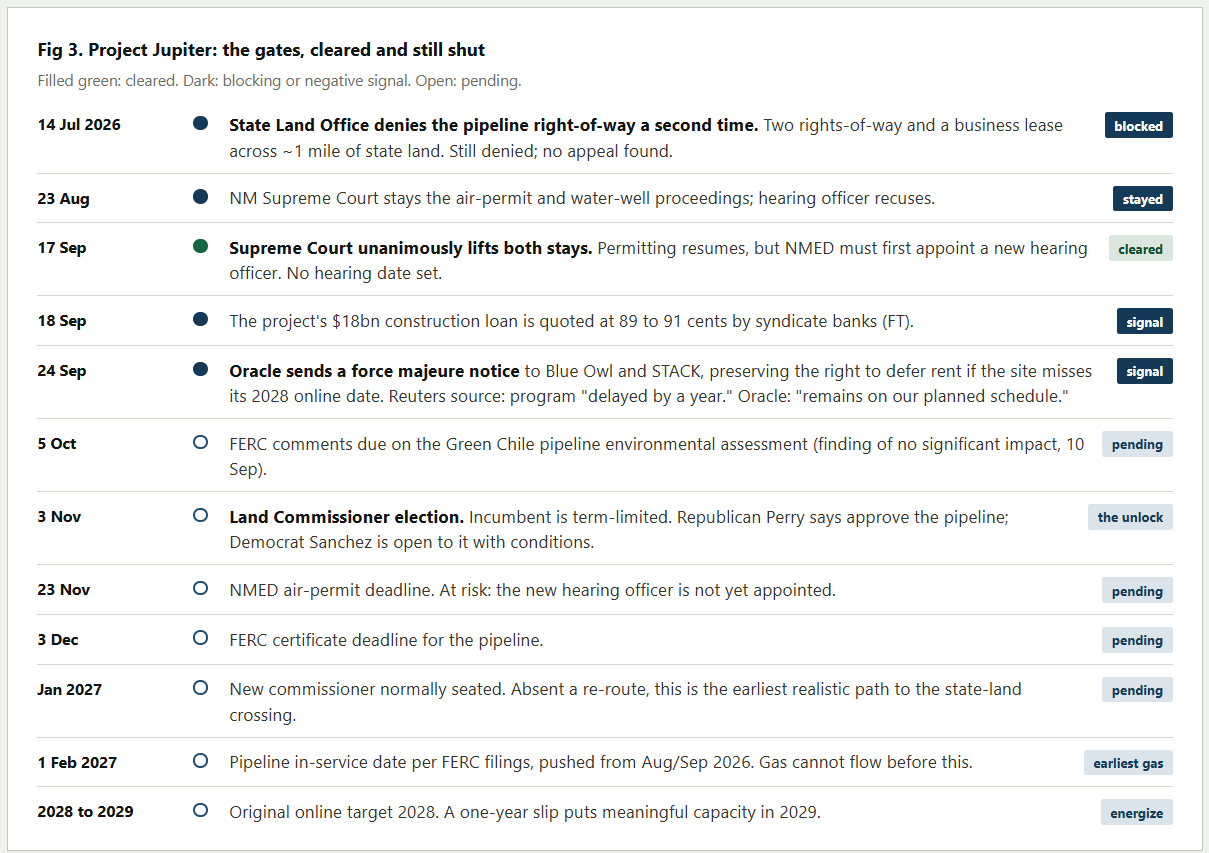
Resolution… The realistic unlock is political, not legal. The commissioner who denied the crossing twice leaves office… her successor is chosen on Nov 3 and is likely seated in January. If the new commissioner approves, and the air permit and FERC certificate land on time, gas could flow from February 2027 and first power follows later in 2027 at the earliest. The base case, consistent with Oracle’s force majeure notice and the reported one-year slip, is meaningful capacity in 2029. No party has given a first-energization date.
Texas froze too… Gov. Abbott paused ERCOT interconnection for data centers on Aug 3 pending an audit, then on Sep 21 ordered TCEQ to halt all data-center permits until it finishes (expected around December). ERCOT’s large-load study for 66 GW of base load now reads “TBD.” Whether sites already under construction are affected is unclear
PJM cleared its 2028/29 auction 6.8 GW short, at the cap. An emergency backstop auction runs Sep 30 to Oct 21
Equipment… Siemens Energy’s gas-turbine backlog is ~69 GW, with lead times of three years or more
Each of these pushes energized supply to the right. That widens the shortage window in the main note’s Fig 5 and raises the value of megawatts that are already powered and permitted.
Putting it together…
Structure unchanged, window widened… Jupiter, Texas and PJM all extend scarcity into 2028 and plausibly 2029
Market picking through winners more closely… reward pricing power, prepayment and owned silicon, avoid volume funded with converts, ATMs and 9% project debt
Powered Texas megawatts got scarcer
Oracle is now a credit watch, not only a capacity story… BBB-, a construction loan at ~90 cents, and a force majeure notice, slip is capacity the rest of the market no longer has to compete with in 2028
Dates to watch
5 Oct: FERC comments close on the Green Chile pipeline
19 Oct: TCEQ status update on the Texas permit freeze
21 Oct: PJM backstop auction bids close; results early December
Late Oct: hyperscaler Q3 prints and first 2027 capex guides
3 Nov: New Mexico Land Commissioner election
Early Nov: Nebius, CoreWeave, IREN and the landlords report Q3
23 Nov / 3 Dec: NMED air-permit deadline / FERC certificate deadline
1 Jan 2027: Colossus termination windows open (Anthropic, Google)
1 Feb 2027: earliest gas to Project Jupiter
DISCLOSURE
Position: At the time of publication, the author holds a positions in GOOGL and NBIS.
Trading Policy: The author will not materially alter this position within 48 hours of publication. After this period, the author may buy, sell, or otherwise adjust the position without further notice. Changes to the author’s view or position will be reflected in subsequent publications when material.
Conflicts: The author has received no compensation from the issuer or any party with a financial interest in this security.
Forward-Looking Statements: This report contains the author’s opinions, estimates, and projections, including price targets derived from financial models. These are forward-looking statements subject to substantial uncertainty. If these assumptions prove incorrect, the actual value may differ materially, including scenarios of significant loss or total impairment. The price target represents the author’s estimate of fair value under the stated assumptions, not a prediction of where the stock will trade.
This report is provided for informational purposes only and does not constitute investment advice. See the full Terms & Disclosures for additional important information.